Long Island Community Hospital $3 Million 401(k) Settlement Who Qualifies for Automatic Payments?
Long Island Community Hospital has agreed to pay $3 million to settle a federal class action in which plan participants say the hospital’s retirement-plan fiduciaries kept employees’ savings in unnecessarily expensive mutual funds and an underperforming stable value fund. The case is Jacobsen et al. v. Long Island Community Hospital et al., No. 2:24-cv-00386-GRB-ST, in the U.S. District Court for the Eastern District of New York.
The settlement covers participants in the Brookhaven Memorial Hospital Medical Center d/b/a Long Island Community Hospital Retirement Savings Plan between January 18, 2018 and September 24, 2026 who held at least one of six challenged funds. No general claim form is required. Payments are calculated from plan records if the court grants final approval.
The key dates are December 9, 2026 (objections), December 24, 2026 (notice of intent to appear), December 25, 2026 (optional rollover form for former participants) and January 8, 2027 at 12:00 p.m. (final approval hearing). The hospital, now NYU Langone Hospital—Suffolk, denies wrongdoing.
Long Island Community Hospital $3 Million ERISA Settlement Quick Facts
| Detail | Official settlement information |
| Settlement amount | $3,000,000 |
| Case | Nichole Jacobsen et al. v. Long Island Community Hospital et al. |
| Case number | 2:24-cv-00386-GRB-ST |
| Court | U.S. District Court, Eastern District of New York |
| Law involved | Employee Retirement Income Security Act (ERISA) |
| Covered period | January 18, 2018 to September 24, 2026 |
| Requirement | Held at least one of six challenged funds |
| Status | Preliminarily approved |
| General claim form | Not required |
| Current participants | Automatic credit to the retirement account |
| Former participants | Check, or optional rollover |
| Former-participant minimum | $10 (payments of $9.99 or less are not made) |
| Objection deadline | December 9, 2026 |
| Notice of intent to appear | December 24, 2026 |
| Rollover form deadline | December 25, 2026 |
| Final approval hearing | January 8, 2027, 12:00 p.m. Eastern |
| Administrator | RG/2 Claims Administration LLC, 1-866-742-4955 |
| Official settlement website | licherisasettlement.com |
Who Qualifies for the Long Island Community Hospital Retirement Plan Settlement?
You may qualify if you took part in the plan during the covered period and held money in at least one of the six challenged funds. The class includes current participants, former employees, beneficiaries and alternate payees under a Qualified Domestic Relations Order (QDRO). Defendants, their immediate families, and hospital officers and directors during the class period are excluded.
Working at the hospital is not enough by itself. You must have held a qualifying fund during the class period.
Do former Long Island Community Hospital employees qualify?
Yes. Former employees may qualify even if they no longer work at the hospital or have closed their accounts. The administrator uses historical plan balances to decide eligibility and calculate shares.
Does the settlement include NYU Langone Hospital—Suffolk employees?
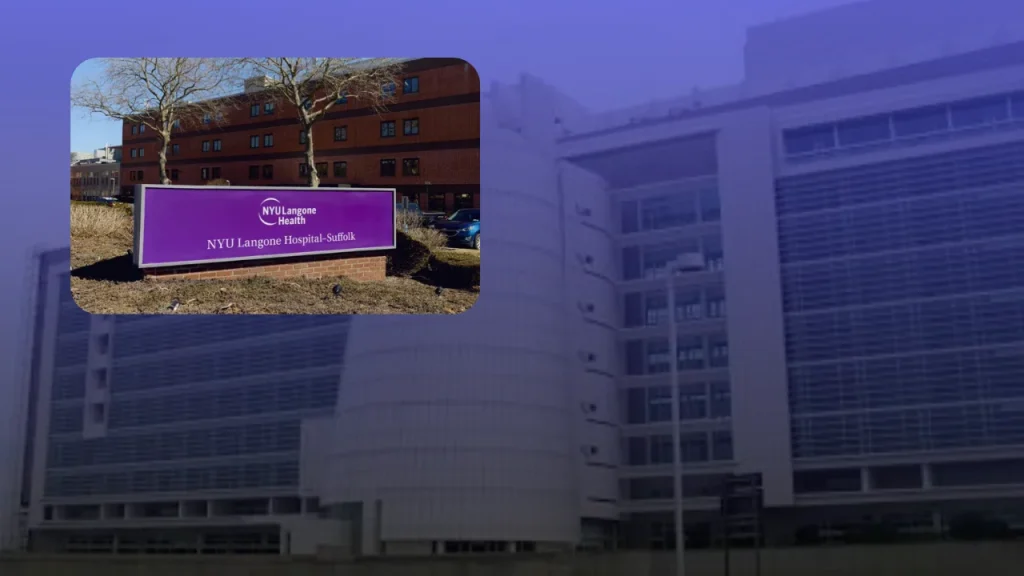
Only if they took part in this specific plan and held a qualifying fund during the class period. Long Island Community Hospital merged with NYU Langone Health on March 3, 2025, and the new name does not by itself exclude anyone. Working at another NYU Langone facility, or being in a different retirement plan, does not create eligibility.
Which Six Retirement Funds Qualify in the Jacobsen v. Long Island Community Hospital Settlement?
| Eligible fund | Share class or type |
| Janus Henderson Enterprise Fund | T |
| MFS New Discovery Value Fund | R3 |
| John Hancock Disciplined Value Mid Cap Fund | I |
| American EuroPacific Growth Fund | R4 |
| Dreyfus Strategic Value Fund | I |
| Prudential Guaranteed Income Fund | Stable value fund |
You need to have held only one of them at some point in the period. If you moved your money out of a fund before the period ended, you may still qualify, because the settlement uses historical records. If you never held any of the six, you generally do not qualify. If you cannot tell which funds you held, ask the administrator.
Why Was Long Island Community Hospital Sued Under ERISA Over Its Retirement Plan?
The lawsuit was filed in January 2024 by plan participants including Nichole Jacobsen, Katherine King, Deborah Dalrymple, Laura Phillips and Jeffrey Hunter. They accused the hospital and its retirement-plan committee of failing to monitor investment costs and performance.
Allegation 1: unnecessary fund fees. The plaintiffs said the plan offered higher-cost share classes when cheaper versions of the same funds were available. As one example, the complaint alleges that Janus Henderson Enterprise Fund T shares had an expense ratio of about 0.92% in 2018, compared with about 0.67% for N shares. An expense ratio is the annual cost of running a fund as a percentage of assets, and higher fees can reduce long-term growth.
Allegation 2: an underperforming stable value fund. The plaintiffs challenged the Prudential Guaranteed Income Fund, saying it paid lower crediting rates than comparable options. The complaint reports rates of 1.65% (2018), 1.55% (2019), 1.15% (2020), 1.05% (2021) and 1.35% (2022).
The defendants deny breaching any duty. The $3 million settlement is not a finding that the investments were unlawful or that the hospital violated ERISA.
What ERISA Provisions and Court Decisions Apply to the Long Island Community Hospital Settlement?
- 29 U.S.C. § 1104 (ERISA § 404). Fiduciaries must act prudently and in the interest of participants, including by evaluating investment options and monitoring costs. In Tibble v. Edison International, 575 U.S. 523 (2015), the Supreme Court addressed a fiduciary’s continuing duty to review plan investments and remove imprudent ones.
- 29 U.S.C. § 1109 (ERISA § 409). Fiduciaries who breach certain duties may have to restore plan losses.
- 29 U.S.C. § 1132 (ERISA § 502). Participants and beneficiaries may bring civil actions to enforce ERISA rights.
For a different retirement-plan case, see Capital One $9.6M ERISA Settlement, Current & Former Employees Could Get Paid. It involves a separate plan and different allegations.
How Much Will Eligible Long Island Community Hospital Plan Participants Receive?
The gross fund is $3 million, but not all of it goes to participants. Fees and costs, subject to court approval, come out first.
| Proposed deduction | Maximum requested |
| Attorneys’ fees | $1,000,000 |
| Litigation expenses | $100,000 |
| Awards to three class representatives | $7,500 each |
| Awards to two other class representatives | $5,000 each |
| Administration costs and applicable taxes | Not yet finalized |
The five awards total $32,500. If the court approves the maximum fees, expenses and awards, about $1,867,500 would remain before administration costs and taxes. The final distributable amount is not yet set.
How will individual payments be calculated?
Under the proposed Plan of Allocation, the administrator generally looks at amounts held in the challenged funds at year-end during the class period. For 2026 it may use the balance at preliminary approval or the second-quarter statement, depending on records, and special rules cover people who closed accounts early. Each person’s share is roughly their qualifying historical balances divided by everyone’s, multiplied by the net fund. That is an explanation, not a way to compute a guaranteed payment. There is no fixed amount per participant, and larger qualifying balances can mean larger payments.
Is there a minimum payment for former participants?
Yes. Former participants whose share is $9.99 or less are not paid. Those at $10 or more may receive a check or a rollover. Current participants with a calculated share of zero receive nothing.
Related article: Arizona Chauffeur Wage Class Action Revived, Ninth Circuit Rules on Unpaid Work and Overtime
How Will Long Island Community Hospital Settlement Payments Be Made?
There is no ordinary claim form. The delivery method depends on whether you have an active plan account on the calculation date.
| Participant category | Default payment | Optional action |
| Active participants (balance above $0) | Automatic deposit into your existing plan account | None needed |
| Former participants (no active balance, including eligible beneficiaries and alternate payees) | Paper check mailed to your address on file | Submit the Former Participant Rollover Form by December 25, 2026 |
Current participants’ deposits are invested under their account elections or the plan’s default investments. Former participants who have moved should update their address with the administrator. Rollover eligibility and tax-preferred treatment are not guaranteed.
How to Request a Rollover in the Long Island Community Hospital Settlement Before December 25, 2026
- Go to the official website: licherisasettlement.com.
- Download the Former Participant Rollover Form.
- Fill in your details, including the Mail ID or notice number, name and address.
- Identify the receiving retirement account and its financial institution.
- Sign the certifications, including those about QDROs and your authority to receive payment.
- Submit by December 25, 2026, online or by mail to Jacobsen v. Long Island Community Hospital ERISA Settlement, c/o RG/2 Claims Administration LLC, P.O. Box 59479, Philadelphia, PA 19102-9479.
December 25 is Christmas Day, so submit early and confirm receipt with the administrator. The rollover election applies only if you qualify for that method, and an active plan account at the calculation date generally means an account deposit. The form says deceased class members are not eligible for rollover through it, and beneficiaries may need to provide a death certificate and proof of their right to the payment.
Can Long Island Community Hospital Plan Participants Object to or Opt Out of the $3 Million Settlement?
The class is certified under Federal Rule of Civil Procedure 23(b)(1), so you cannot opt out. You can object.
- December 9, 2026: objections. You may object to the settlement, the allocation method, the attorneys’ fees, expenses or the awards. The objection must be received by the court, class counsel and defense counsel and follow the official long-form notice. Objecting does not stop you from being paid if the settlement is approved.
- December 24, 2026: notice of intent to appear. Anyone who wants to speak at the hearing must follow the notice’s procedure by this date. Attending is optional.
- January 8, 2027, 12:00 p.m. Eastern: final approval hearing before Magistrate Judge Steven L. Tiscione, Courtroom 910, U.S. District Court, Eastern District of New York, 100 Federal Plaza, Central Islip, NY 11722. The court will decide whether the settlement is fair, reasonable and adequate and will review objections and the fee requests. The date may change, so check the official site.
When Will Long Island Community Hospital Settlement Payments Arrive?
No payment date has been announced. Payments come only after the court grants final approval and any appeals are resolved, and then the administrator must finalize data and allocations. January 8, 2027 is the fairness hearing, not a payment date.
For another automatic-payment ERISA settlement with its own rollover deadline, see Frontier Communications $14.05 Million 401(k) Settlement, Who Qualifies and the December 8 Rollover Deadline.
Are Long Island Community Hospital 401(k) Settlement Payments Taxable?
It depends on your situation and how you are paid. Under the proposed Plan of Allocation, checks to former participants are subject to applicable withholding and reporting, and deposits into active plan accounts may be treated differently. A rollover into an eligible account may avoid an immediate taxable distribution, but the administrator’s form does not promise that result. Talk to a tax professional about larger amounts. The IRS explains rollovers at IRS Topic 413.
What Happens if You Do Nothing in the Long Island Community Hospital Settlement?
If you qualify, you do not need a claim form to be considered, because the administrator uses plan records. Doing nothing also means accepting the default payment method and the release of covered claims once the settlement takes effect. Because members cannot opt out, eligible members are generally bound by the judgment. Former participants should confirm their address, and anyone who disagrees with the terms should consider the December 9 objection deadline.
For a different hospital-plan settlement with automatic payments, see $850K Dartmouth-Hitchcock ERISA Retirement Plan Settlement, Are You Eligible for a Payment? No Claim Form Required. It involves different investments and employees.
Long Island Community Hospital $3 Million Settlement Timeline
| Date | Event |
| January 18, 2018 | Class period begins |
| January 2024 | ERISA lawsuit filed |
| March 3, 2025 | Hospital merges with NYU Langone Health |
| March 31, 2025 | Third amended complaint filed |
| August 19, 2026 | Parties sign the settlement agreement |
| September 24, 2026 | Class period ends |
| December 9, 2026 | Objection deadline |
| December 24, 2026 | Notice of intent to appear due |
| December 25, 2026 | Optional rollover deadline |
| January 8, 2027 | Final approval hearing, noon Eastern |
| Not announced | Distribution date |
Official Administrator Contact Information for the Long Island Community Hospital ERISA Settlement
RG/2 Claims Administration LLC
Phone: 1-866-742-4955 | Email: [email protected] | Website: licherisasettlement.com
Mail: LICH ERISA Settlement, c/o RG/2 Claims Administration LLC, P.O. Box 59479, Philadelphia, PA 19102-9479
Bottom Line: Long Island Community Hospital $3 Million ERISA Settlement
The proposed settlement could pay eligible current and former plan participants who held one or more of six challenged funds between January 18, 2018 and September 24, 2026. No general claim form is required. Active participants should get credits to their accounts, and former participants get a check unless they elect a rollover. The dates to remember are December 9 (objections), December 25 (rollover) and January 8, 2027 (final approval hearing). The hospital denies wrongdoing, and individual amounts are not yet determined.
Sources
- Official Settlement Website, licherisasettlement.com
- Official Long-Form Notice
- Proposed Plan of Allocation
- Former Participant Rollover Form
- Third Amended Complaint
- Settlement Agreement
- 29 U.S.C. § 1104, 29 U.S.C. § 1109, 29 U.S.C. § 1132
- Federal Rule of Civil Procedure 23
- IRS Topic 413, Rollovers From Retirement Plans
Disclaimer: This is independent legal information, not legal, tax or investment advice. Final approval, payment amounts and timing are up to the federal court.
Researched and written by Israr Ahmad, legal content researcher and founder of AllAboutLawyer.com. All facts verified against the official Long-Form Notice, Plan of Allocation, Rollover Form and settlement website run by the administrator (licherisasettlement.com), as of November 19, 2026. Last Updated: November 19, 2026.
About the Author
Israr Ahmad is a legal content researcher with 4+ years of experience covering class action settlements and consumer rights cases. He has researched and published coverage of 2,500+ settlements using verified court records, settlement administrator filings, and government sources. Learn more about Israr.